Federal Reserve raises interest rates for the first time since 2023

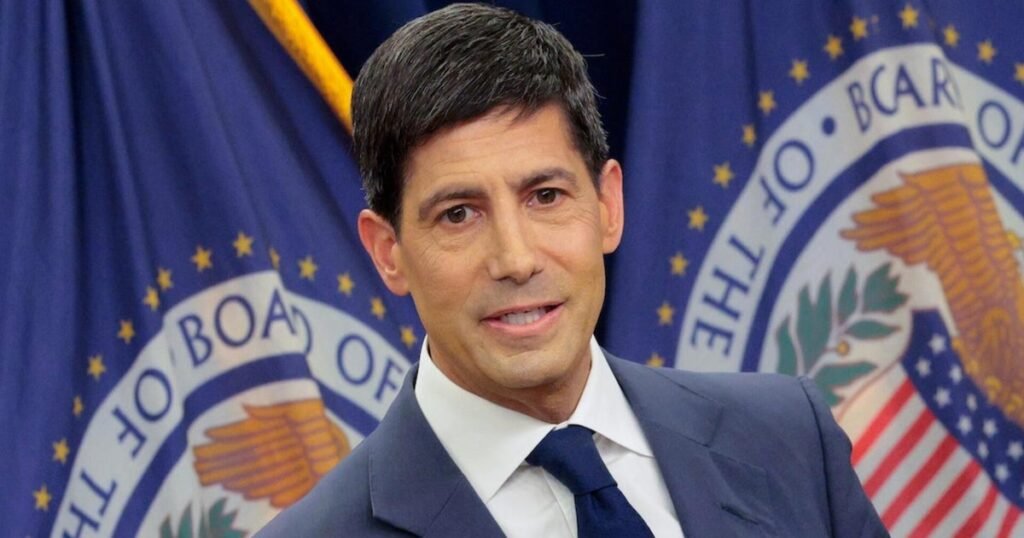
The Federal Reserve raised interest rates for the first time since 2023 on Wednesday, reversing course as the Iran war drives up global energy prices and fuels inflation.
The Fed raised the federal funds rate by 0.25 percentage points, bringing its target range to between 3.75% and 4% — its highest level since December 2025. The benchmark rate influences borrowing costs across the U.S. economy, including for credit cards, auto loans and personal loans.
In a set of quarterly projections, the Fed also signaled that its rate-setting committee expects to again raise rates later this year. The vote to raise the benchmark rate was unanimous, the Fed said in a statement on Wednesday.
The hike marks an about-face from the Fed’s stance at the start of the year, when inflation was cooling, and as many economists expected the central bank to lower interest rates throughout 2026. Instead, monetary policymakers are brandishing their most potent weapon to curb prices. The Consumer Price Index rose at an annual rate of 3.4% in August, far above the Fed’s 2% annual target.
“Inflation remains elevated. Today’s policy action will support a timelier return to the Committee’s 2 percent goal,” the Fed said its statement.
Fed Chairman Kevin Warsh will answer questions about the central bank’s latest policy statement in a news conference at 2:30 p.m. ET.
President Trump has repeatedly called on the Fed to lower borrowing costs. But escalating conflict in the Middle East has disrupted crude oil production and supplies, pushing up fuel prices in the U.S. and driving up costs across the broader economy.
The average price of diesel reached a record $6.31 per gallon on Wednesday, a 71% jump from a year ago, according to AAA. Gasoline now averages $4.37 a gallon, up from $4.06 a month ago and $2.98 just before the Iran war started in February.
Higher interest rates can tamp down inflation because consumers pare spending and businesses reduce investment. That cools economic growth and tempers price increases as demand slows.
More hikes to come?
Wednesday’s rate hike was widely expected by economists and investors. Attention is now turning to whether the increase will mark the first in a series of hikes, with the Fed’s economic projections on Wednesday signaling its members foresee an additional hike before year-end.
“One more hike this year in December is our base case, although this remains contingent on upcoming CPI reports and the path of energy prices,” Kay Haigh, global head and CIO of fixed income and liquidity solutions at Goldman Sachs Asset Management, said in an email after the Fed’s announcement.
Because of stubbornly high inflation, some economists expect the Fed to follow with one or two more rate hikes later this year and into early 2027.
“People need to plan for months of elevated borrowing costs, and treat a single Fed meeting as one step in a longer process rather than an ending,” said Nigel Green, the CEO of the deVere Group, an investment firm, in an email.
Still, economists don’t expect a repeat of the Fed’s aggressive tightening efforts that began in 2022, when inflation hit a 40-year peak of 9.1% as the economy was rebounding from the pandemic. The central bank raised rates 11 times during the period, lifting its benchmark from near zero to between 5.25% and 5.5% by July 2023.
Since then, the Fed has either cut or held rates steady.
Higher borrowing costs
Banks are likely to respond to the latest Fed hike by boosting their interest rates on credit cards and other lending products, although a single 0.25 percentage-point increase might not significantly raise borrowing costs, according to financial experts.
Even so, the increase in borrowing costs comes as Americans are shouldering higher costs for gas, food and other essentials.
“Consumer sentiment is now 13% below where it was this time last year,” said Heather Boushey, professor of practice at the Kleinman Center for Energy Policy at the University of Pennsylvania, in an email. The Fed’s rate hike this week “will make it harder for families to borrow, raising the cost of car loans, credit cards, mortgages and more.”
You may be interested
Robert Kraft Responds to Macklemore Invite to Match $1 Million Donation
new admin - Sep 16, 2026[ad_1] Hours after Macklemore challenged Robert Kraft “to match” his $1 million donation to organizations supporting Palestinians, the billionaire New…
House passes bill to shield Americans from data center energy costs
new admin - Sep 16, 2026Washington — The House on Wednesday overwhelmingly passed legislation aimed at protecting Americans from shouldering the potential costs of data…
Terrell Owens compares Jerry Jones to Donald Trump, says Cowboys owner shows signs of ‘narcissism’
new admin - Sep 16, 2026[ad_1] Cowboys being Super Bowl contenders ‘not a reach’, Will Julian Sayin win the Heisman? | FTF Dallas Cowboys owner…